Business Area
Automotive analytics, electric mobility and competitive market intelligence
Original Automotive Analytics Case Study
Analysing battery electric vehicle registrations, manufacturer competition, model performance and EV portfolio expansion in Germany between 2020 and 2026
Python • Pandas • Matplotlib • Seaborn • KBA Data • Data Cleaning • Data Validation • Market Analysis • Competitive Analysis • Exploratory Data Analysis
This case study examines Germany's battery electric vehicle market using official registration records from the German Federal Motor Transport Authority (KBA). The registration data was enriched with a verified EV model mapping database containing canonical model names, market-entry information, model status, mapping confidence and official manufacturer sources.
Automotive analytics, electric mobility and competitive market intelligence
3,334 unique EV registration records after removing 40 exact duplicates
Germany's leading EV manufacturers, verified model series and reporting years from 2020 to 2026
Python, Pandas, Matplotlib, Seaborn, Excel and official KBA data
Germany's transition toward electric mobility has intensified competition among established automotive manufacturers and dedicated electric vehicle companies. Registration totals alone do not explain which manufacturers are leading, which models are driving adoption or how product portfolios have evolved.
This project transforms official registration data into business insights that can support market monitoring, product strategy, competitive benchmarking and data-driven decision-making.
How has Germany's battery electric vehicle market developed between 2020 and 2026, and which manufacturers, models and vehicle segments have contributed most strongly to its growth?
The project uses an original analysis-ready workbook created by merging KBA registration records with a verified electric vehicle model mapping database. The enrichment process standardised model identities and added official manufacturer references, launch information and confidence levels.
Total registrations and BEV registrations by manufacturer, model series, segment and reporting year
Canonical EV names, production or reveal start, German market year and model status
Mapping confidence, merge status, verification notes and official manufacturer source
Descriptive, exploratory, time-series, competitive and product portfolio analysis
The project follows a structured workflow from source preparation through market interpretation and strategic recommendations.
Loaded the merged KBA and verified EV model database.
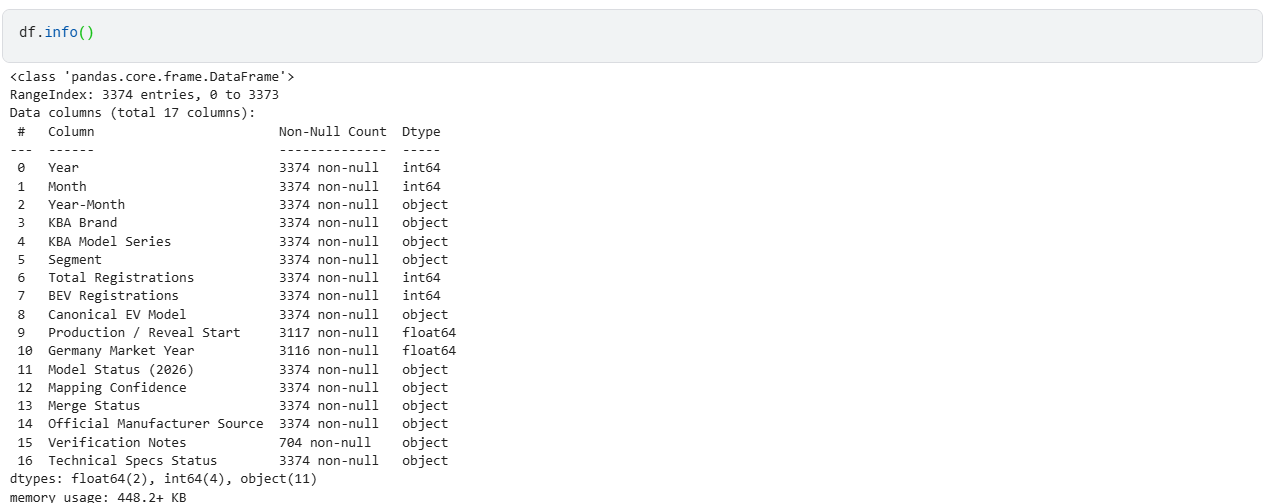
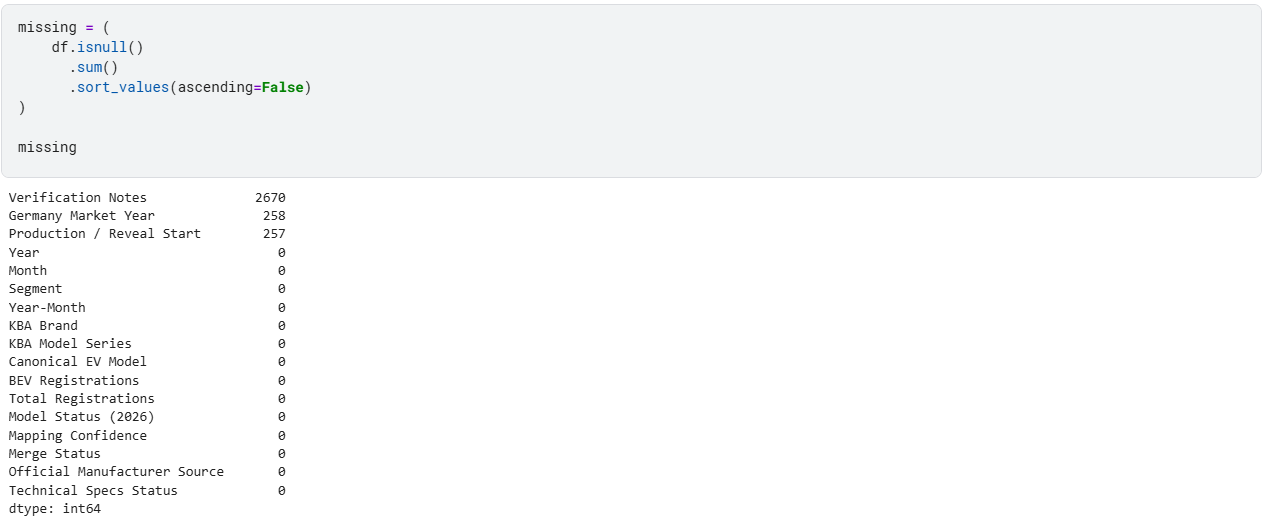
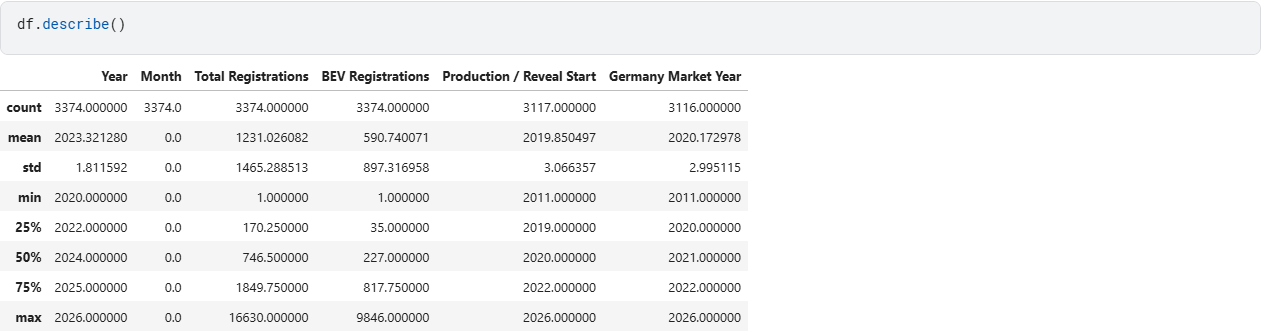
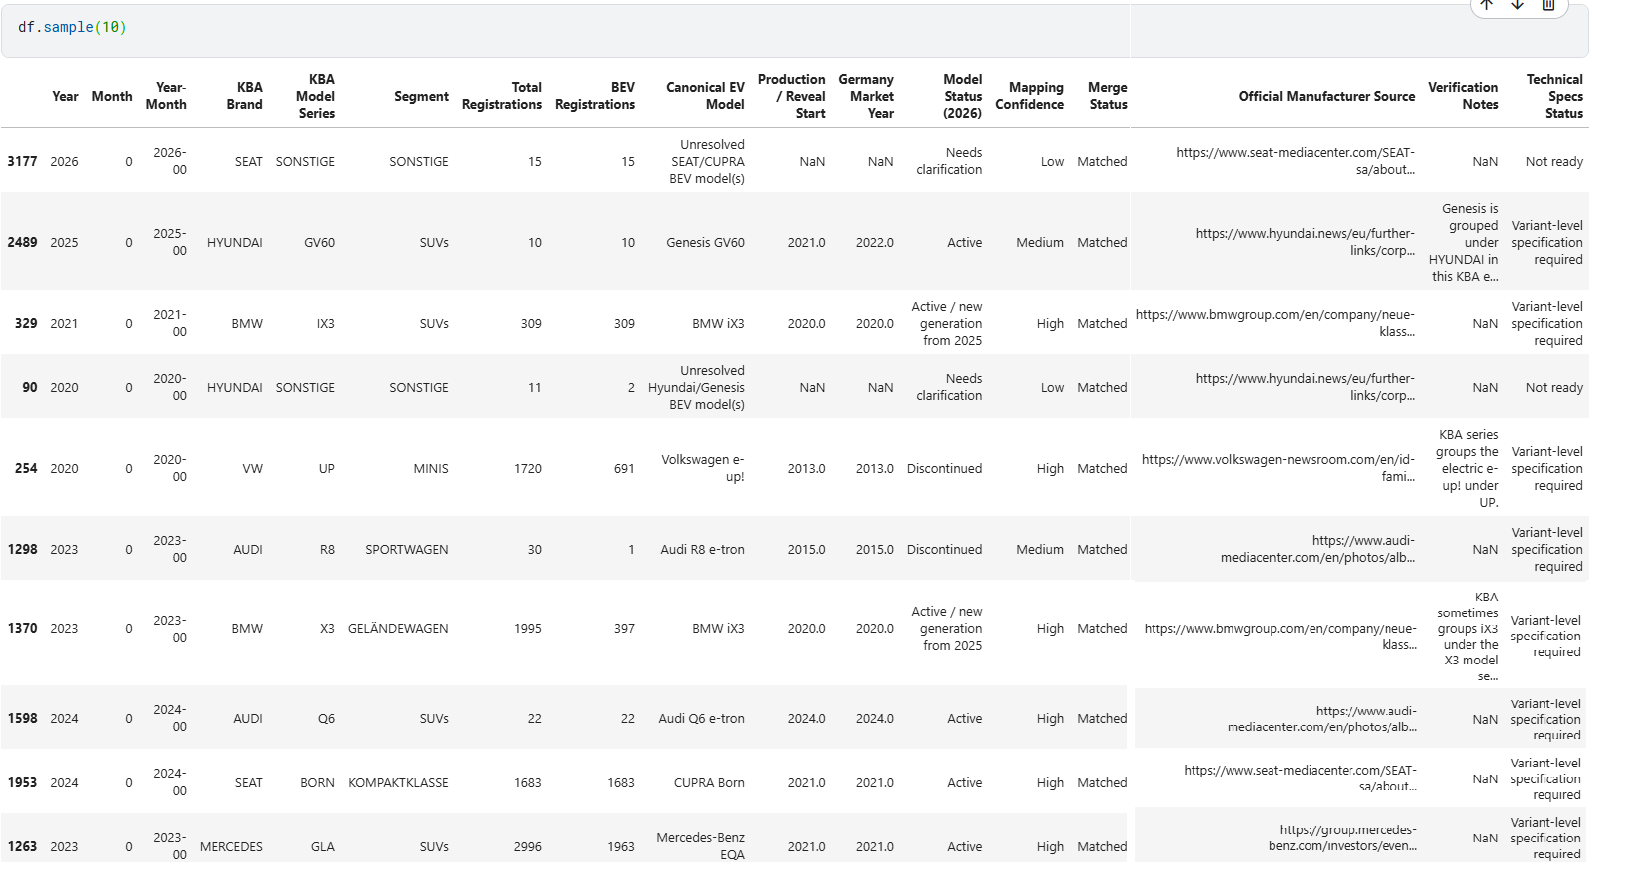
Reviewed structure, types, missing values and statistics.
Investigated quality issues and removed exact duplicates.
Examined trends, brands, models, share and segments.
Evaluated growth and competitive performance.
Converted findings into business recommendations.
Open each stage to explore the Python workflow, screenshots and reasoning.
import pandas as pd
import matplotlib.pyplot as plt
import seaborn as sns

file_path = "/kaggle/input/datasets/ashwinraphel/german-ev-registration/German EV Registration Database 20202026.xlsx"

df = pd.read_excel(
    file_path,
    sheet_name="Merged Monthly EV Data"
)
df.head()
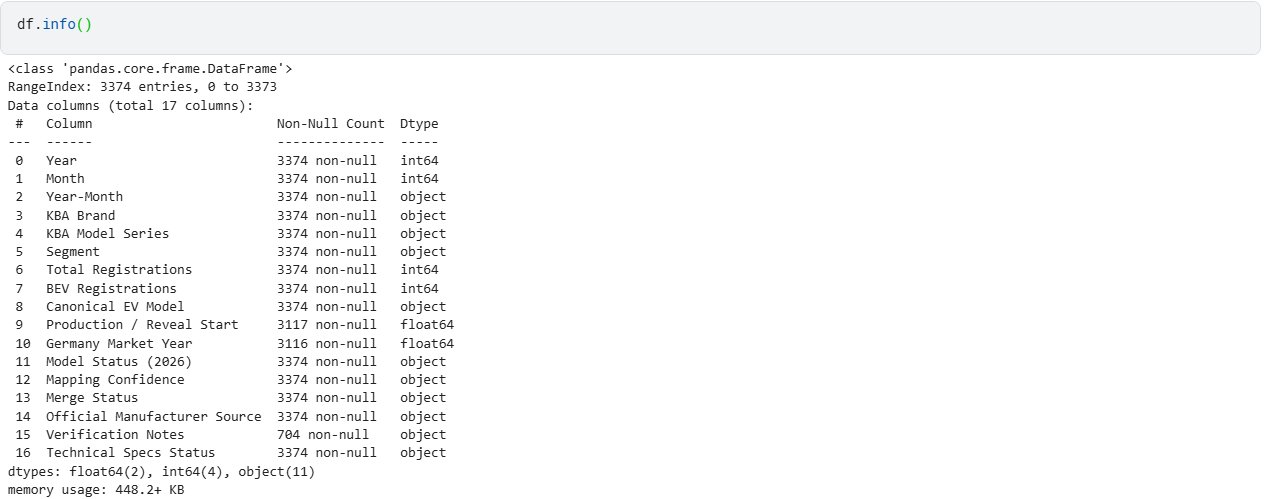
df.info()
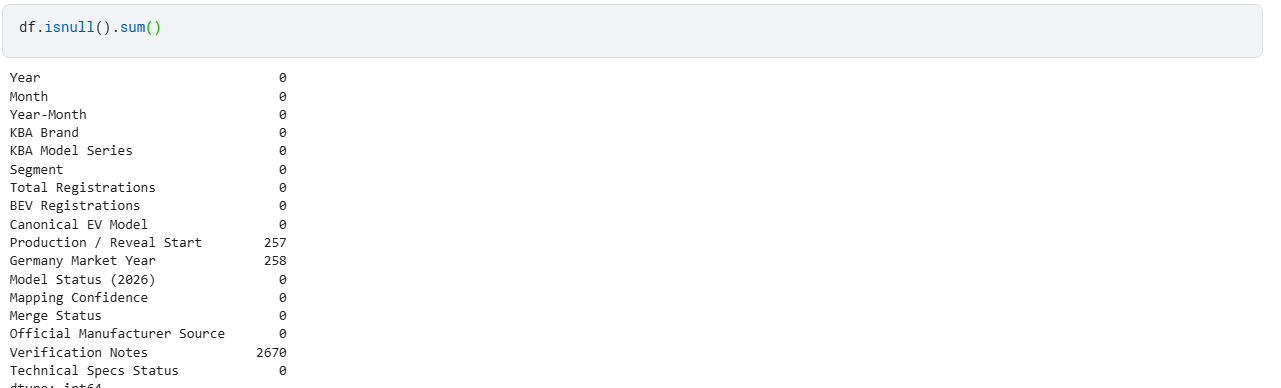
df.isnull().sum()
df.shape

missing = (
    df.isnull()
      .sum()
      .sort_values(ascending=False)
)

df.describe()
df.sample(10)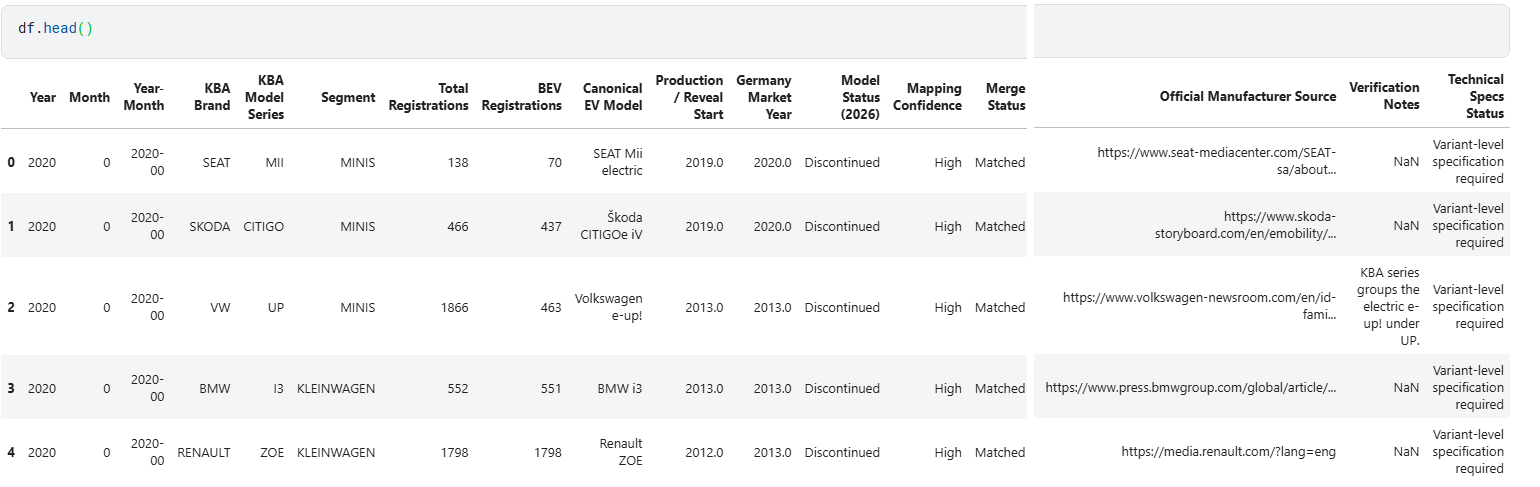

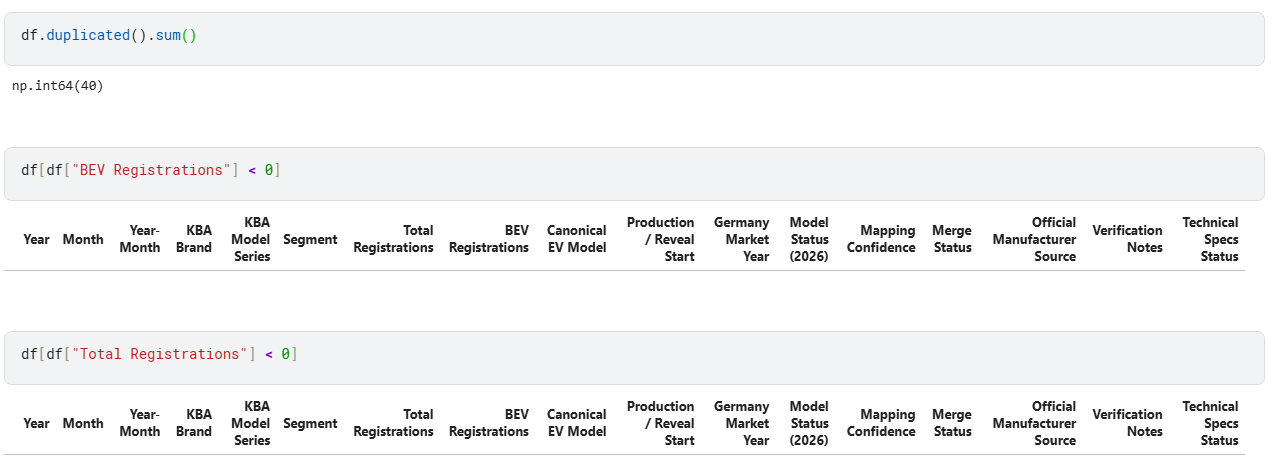
No negative BEV or total registration values were found.
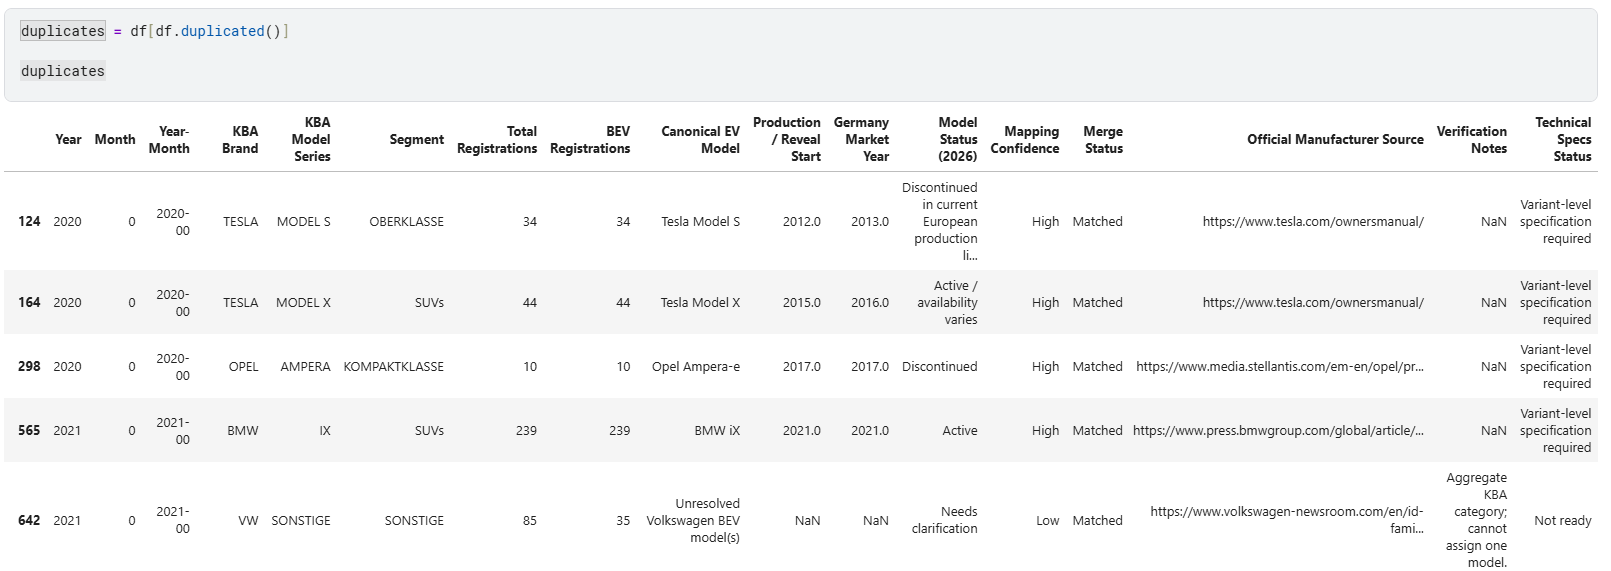
The initial check detected 40 exact duplicate records.
Duplicate rows were reviewed before removal.
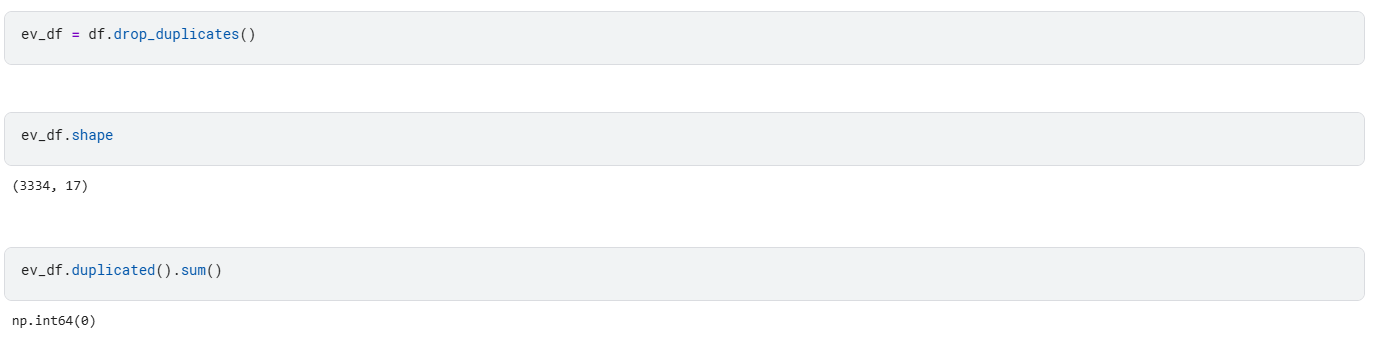
The final dataset contained 3,334 unique rows and zero duplicates.
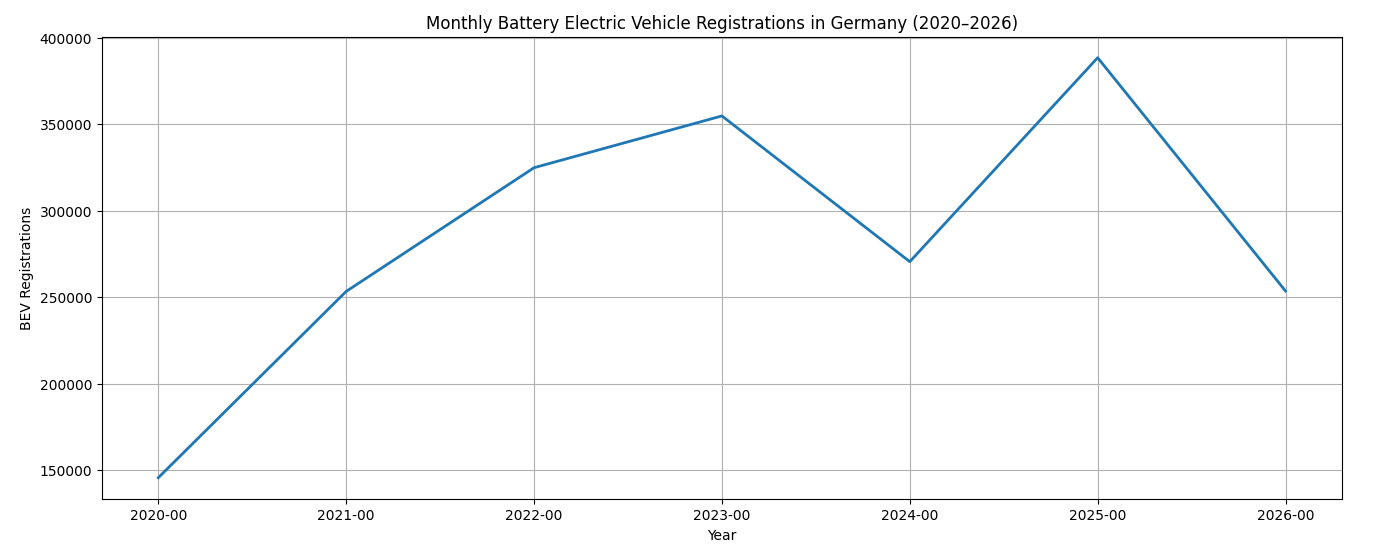
Registrations increased strongly through 2023, declined in 2024 and recovered in 2025.
The long-term direction remains positive, although policy, pricing and supply conditions can produce major fluctuations.
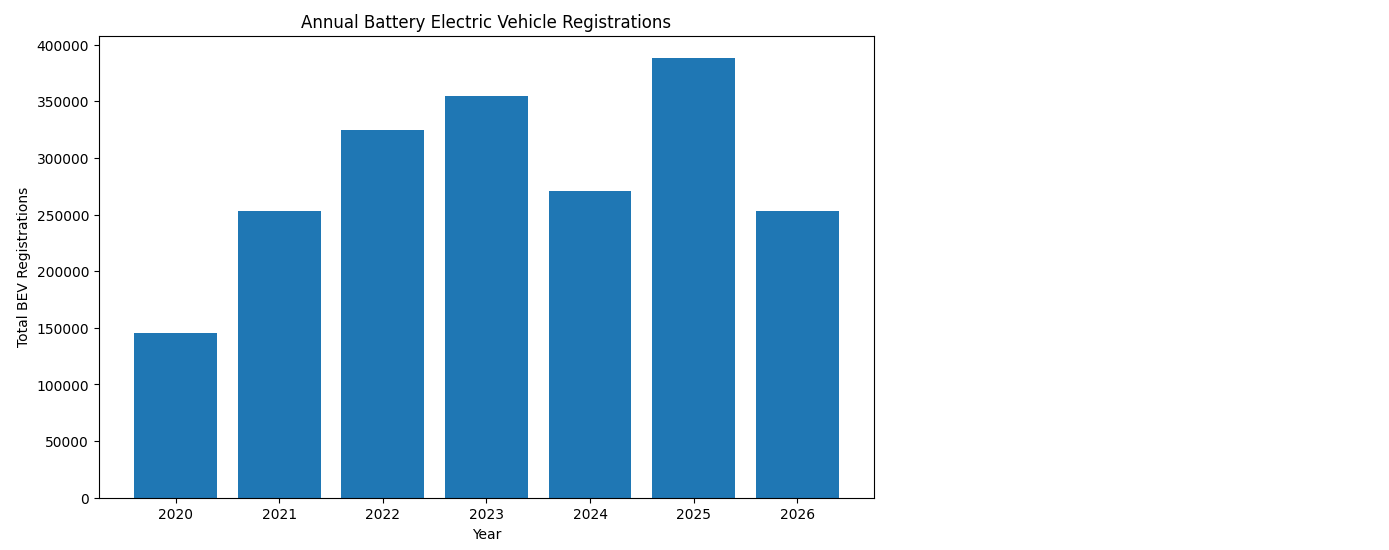
2025 recorded the highest total in the available dataset.
The 2025 recovery suggests renewed market demand after the 2024 contraction.
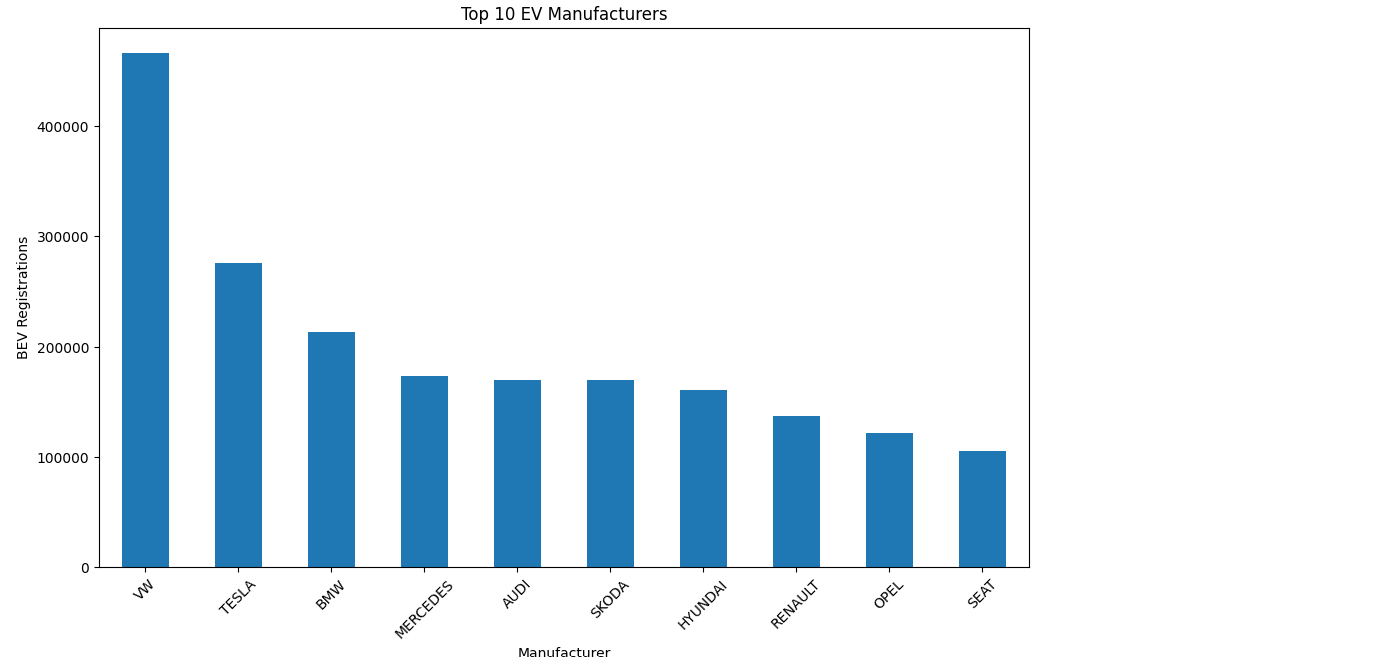
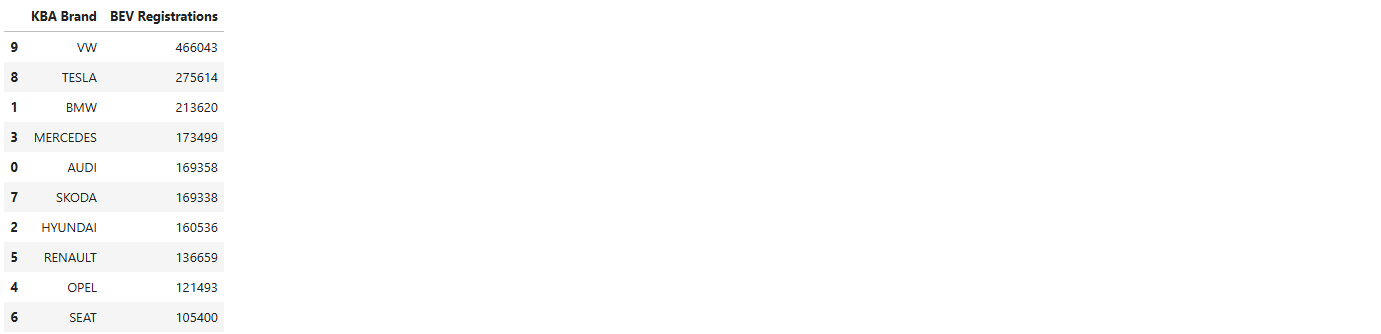
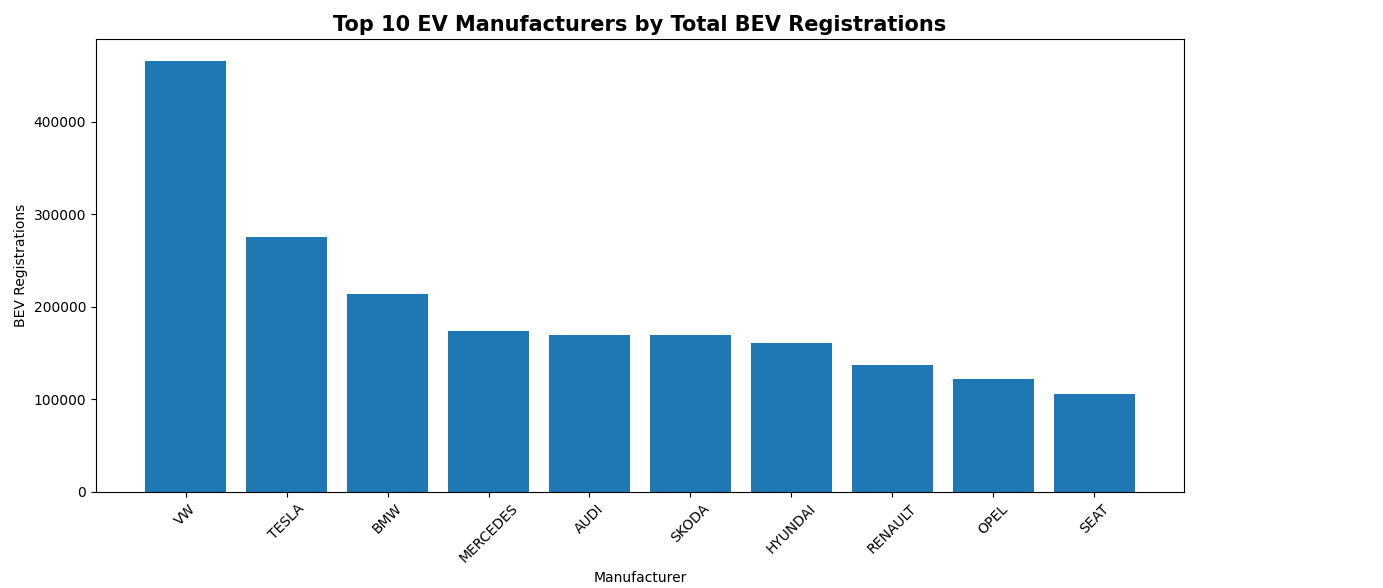
Volkswagen achieved the highest cumulative registrations, followed by Tesla and BMW.
Established German brands and dedicated EV manufacturers both hold strong positions.
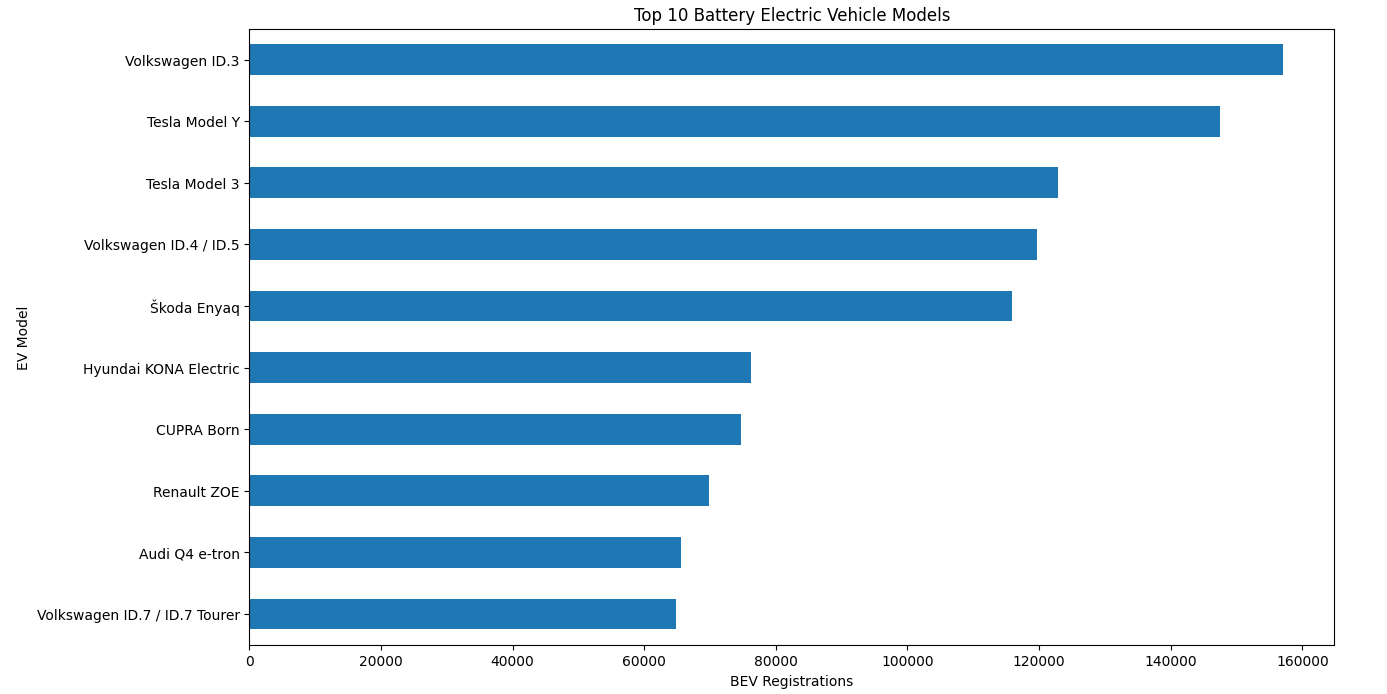
The Volkswagen ID.3, Tesla Model Y, Tesla Model 3 and ID.4/ID.5 family were among the strongest performers.
A limited number of high-volume models contributed substantially to overall EV adoption.
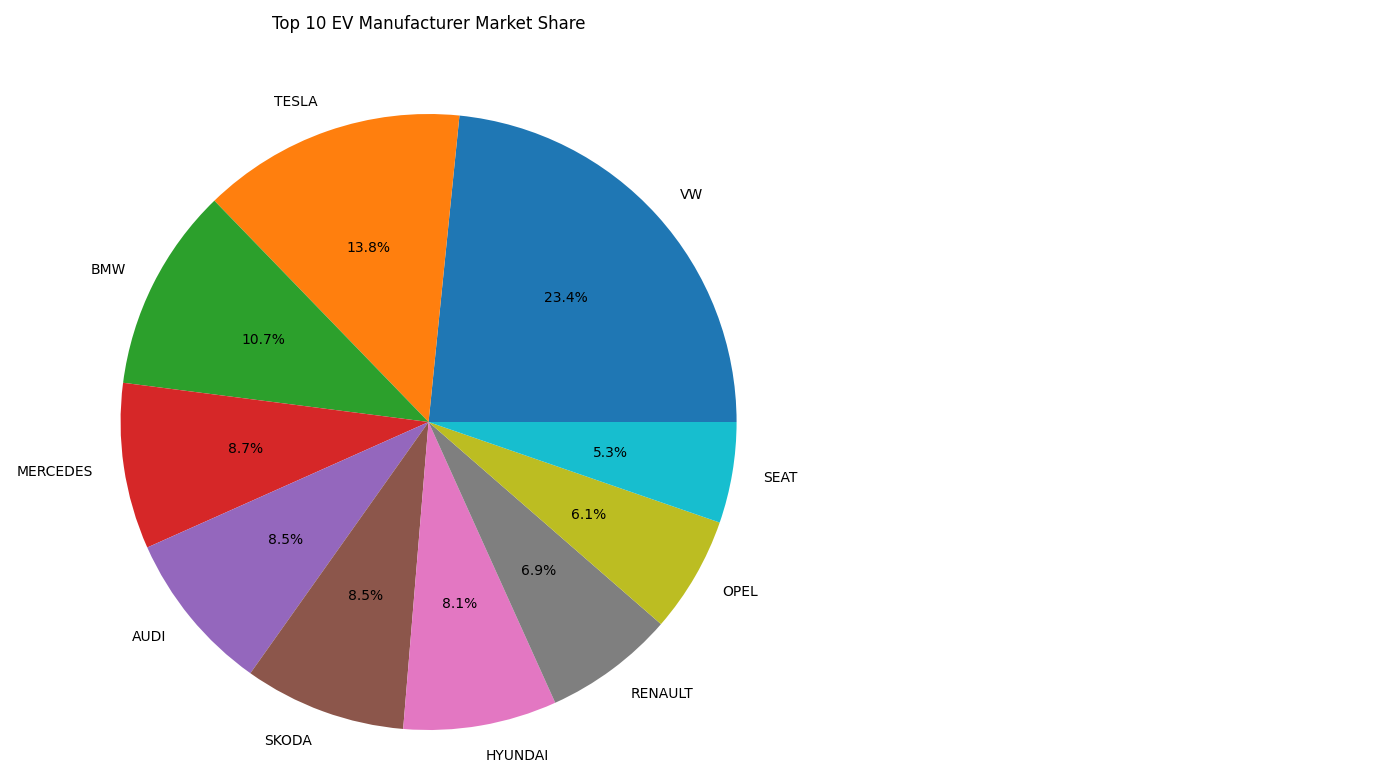
Volkswagen held the largest cumulative share, with Tesla in second place.
The market has a clear leader but remains distributed across several strong competitors.
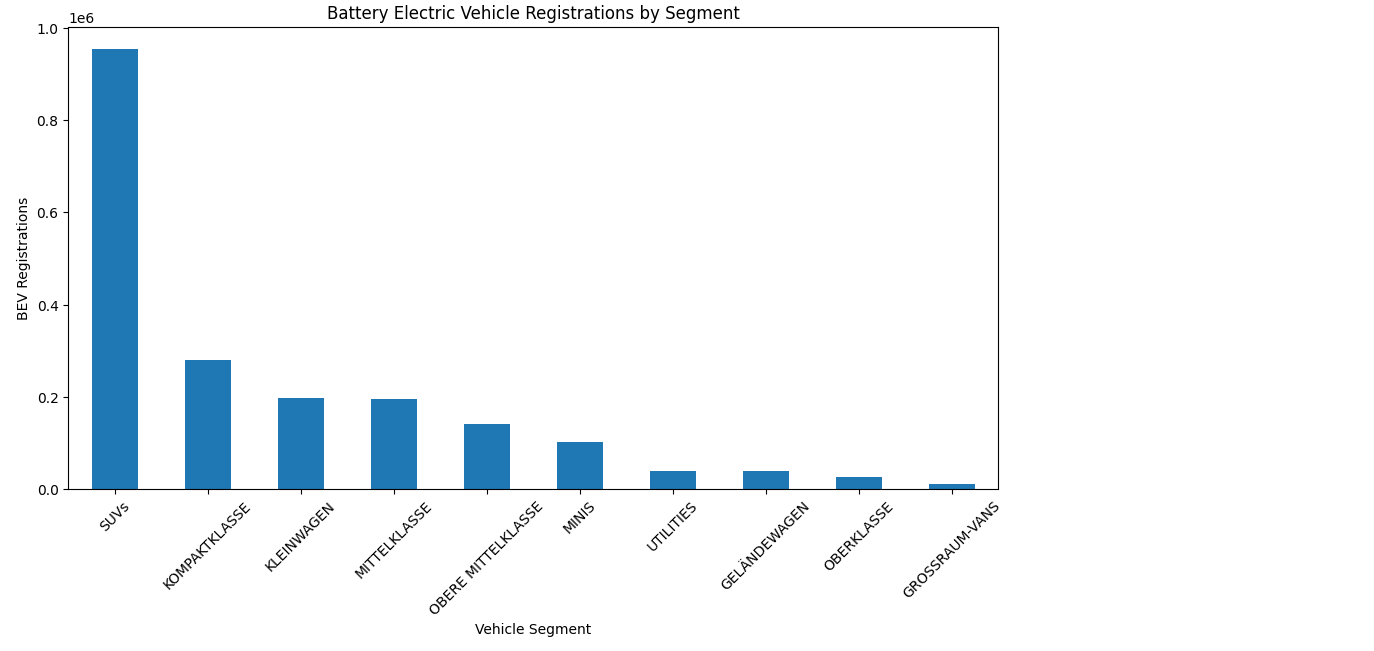
SUVs generated the highest volume by a wide margin.
SUV demand is central to EV product strategy, while compact and small-car segments remain important.
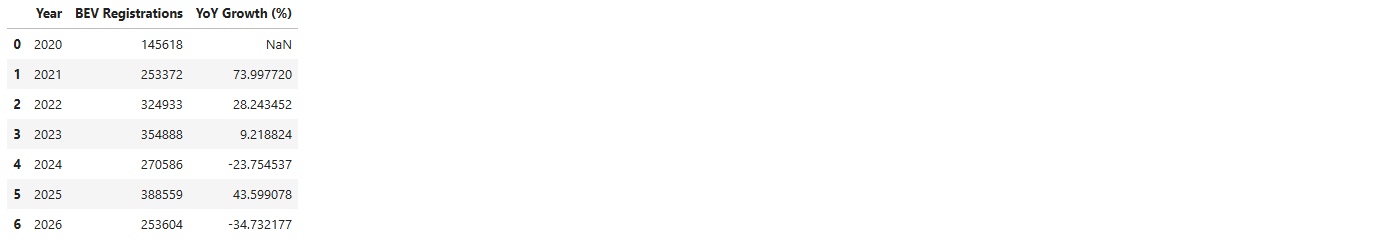
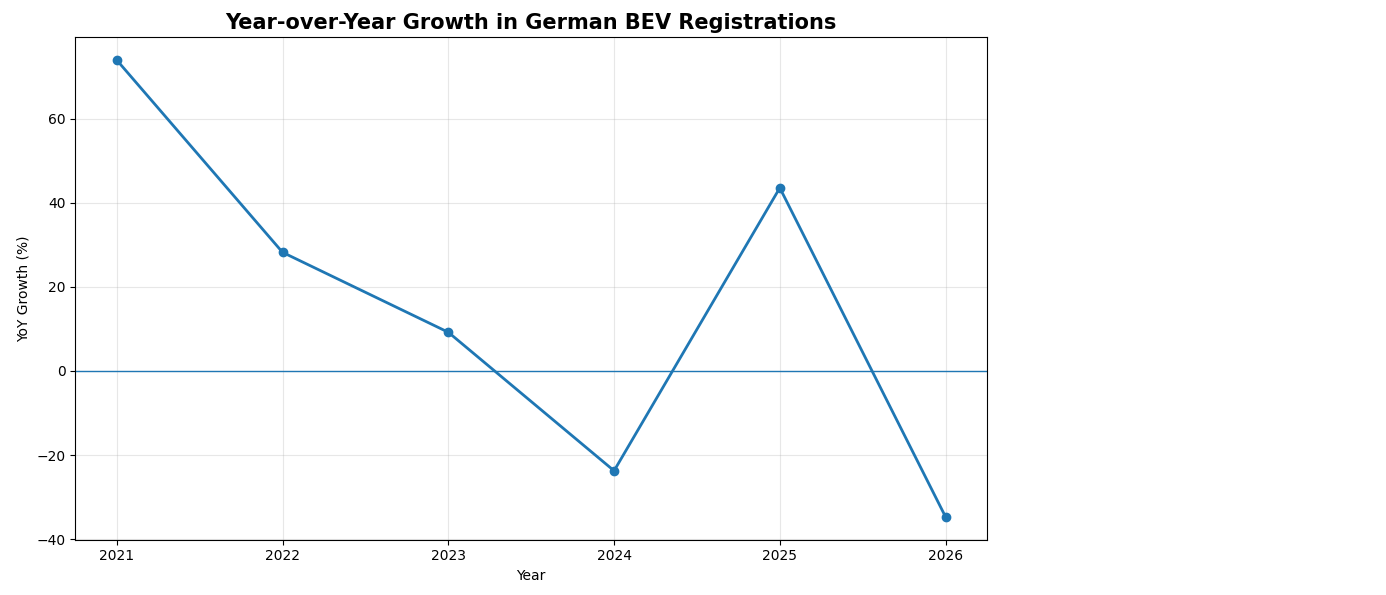
Growth was strongest in 2021, declined in 2024 and recovered in 2025.
Market expansion should be evaluated alongside incentives, product cycles and economic conditions.
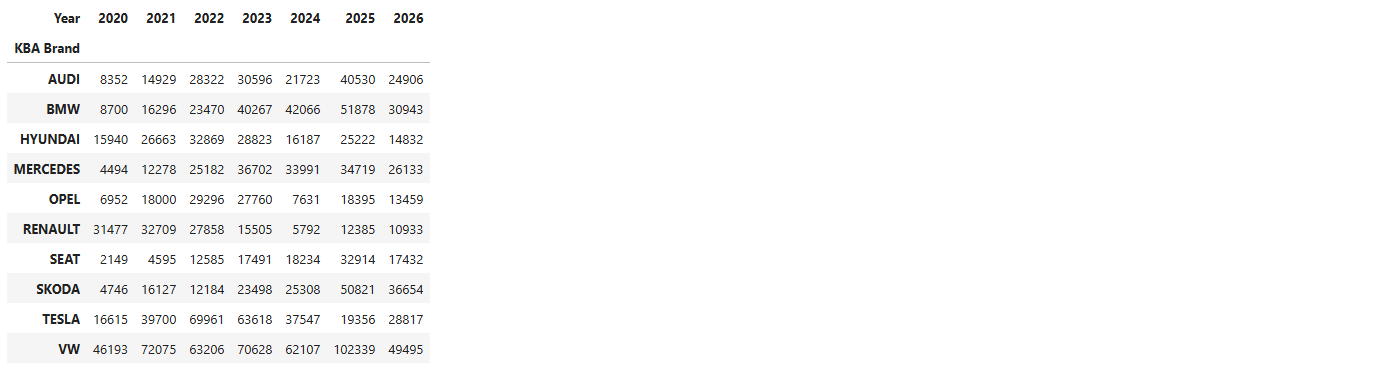
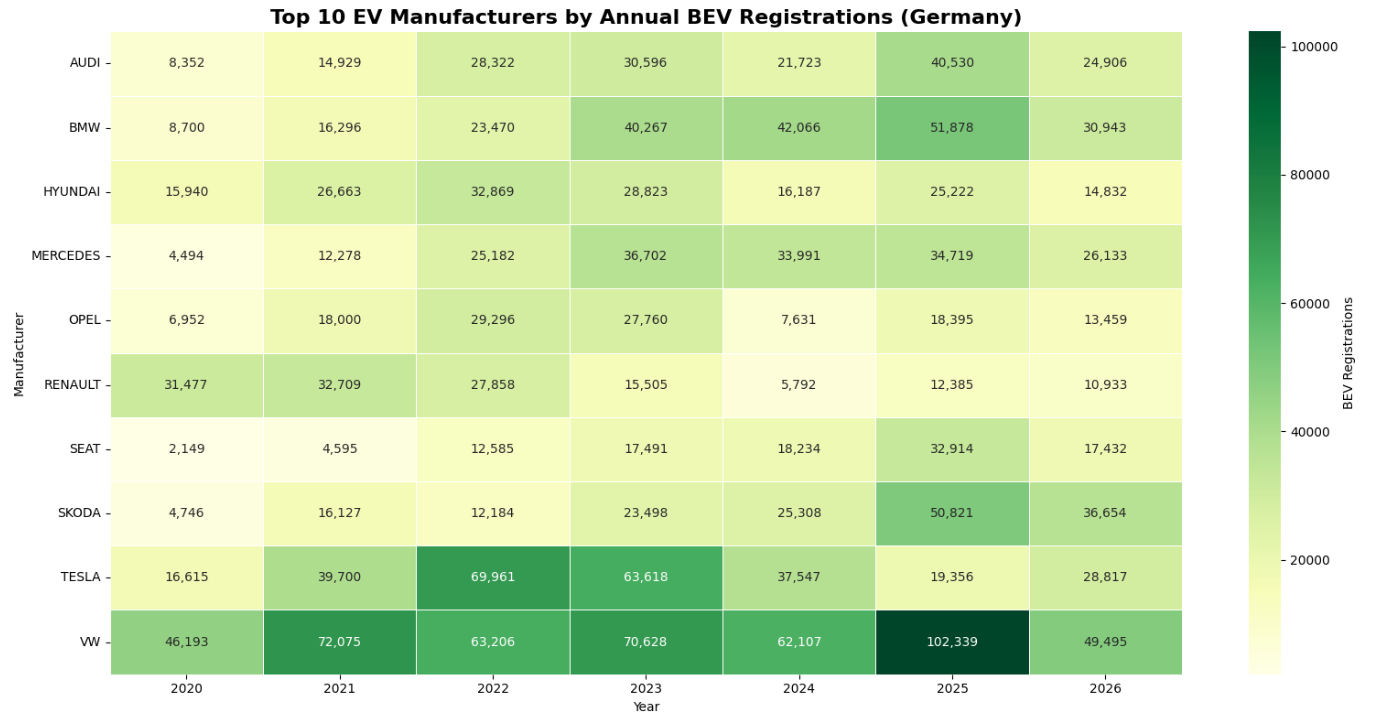
Volkswagen maintained consistently high annual volumes while other brands showed different performance cycles.
The heatmap distinguishes consistent leaders from brands whose results depend more strongly on individual model cycles.
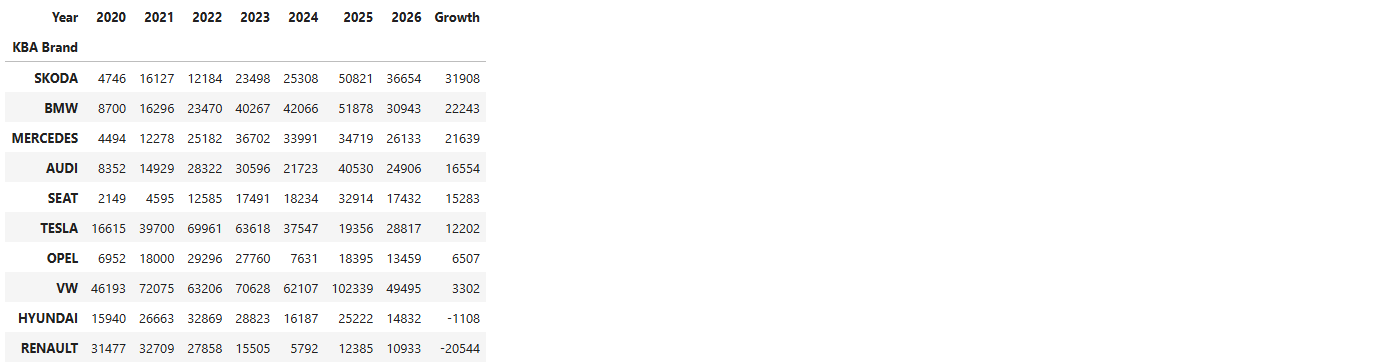
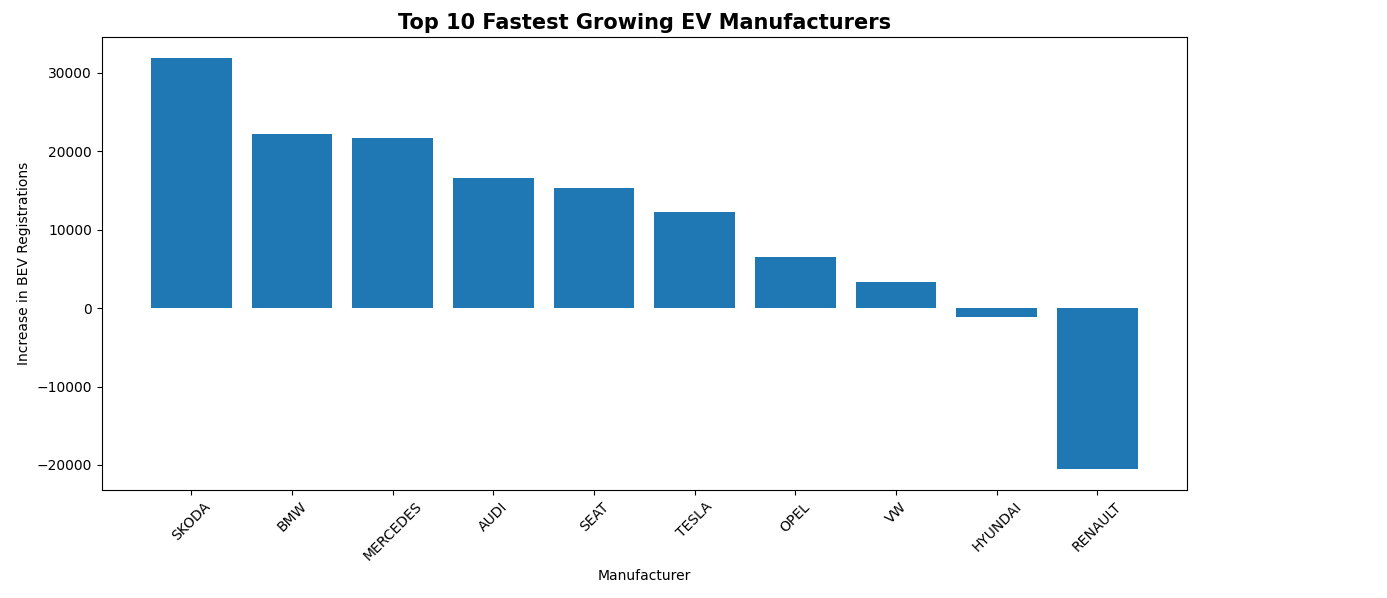
Several manufacturers recorded substantial increases compared with the first reporting year.
Growth can indicate successful launches, stronger acceptance and broader portfolio coverage.
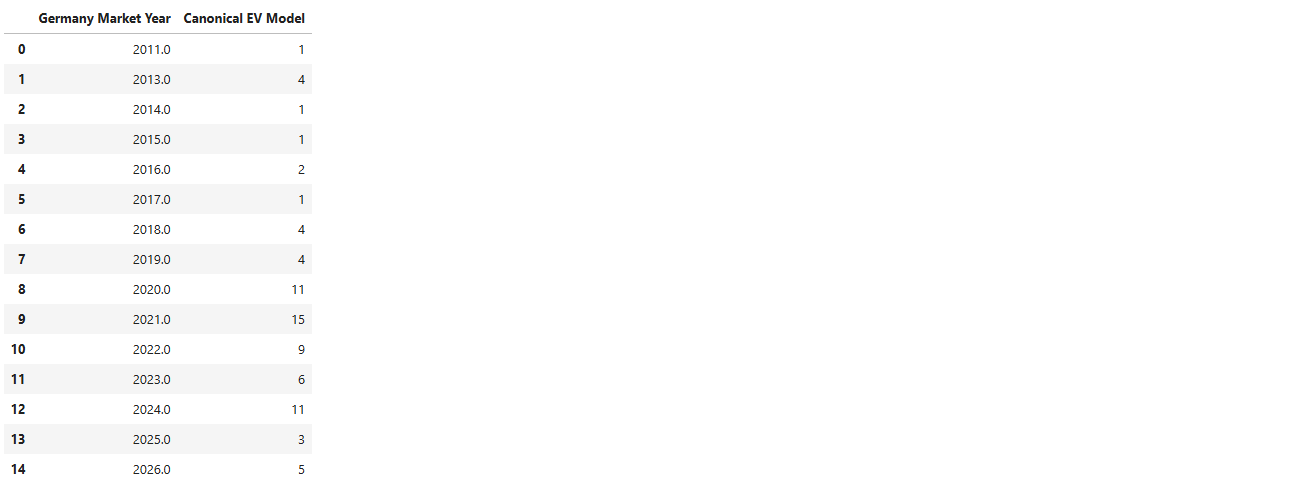
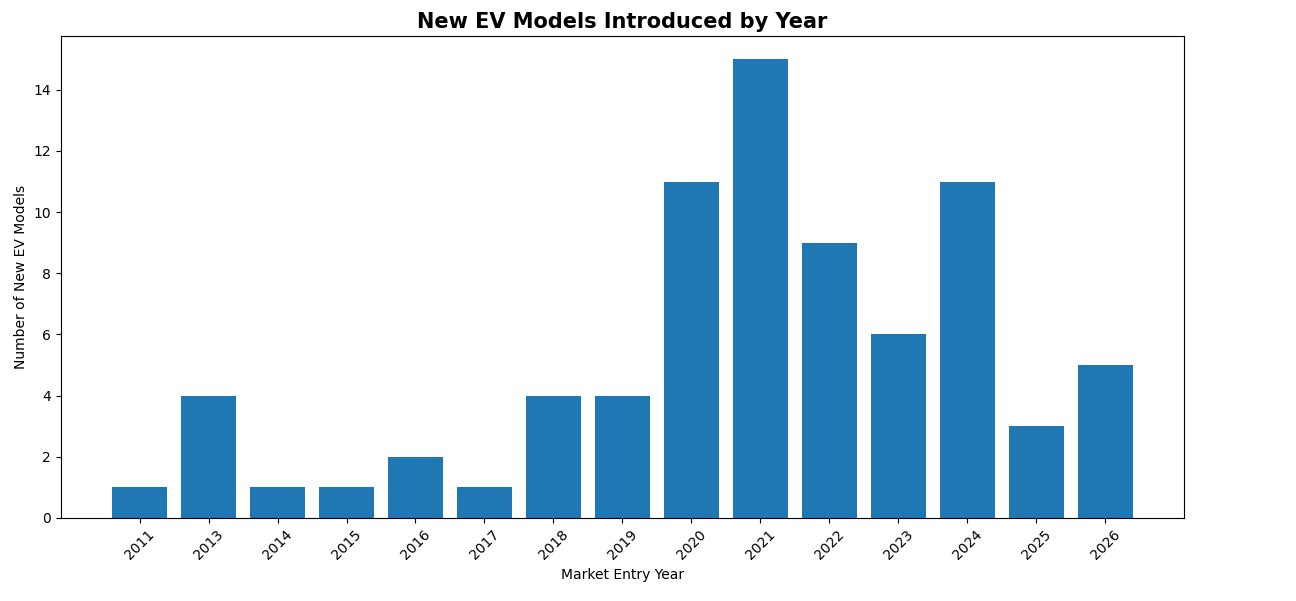
Model introductions accelerated particularly around 2020, 2021 and 2024.
Increasing model availability expands consumer choice and intensifies competition.
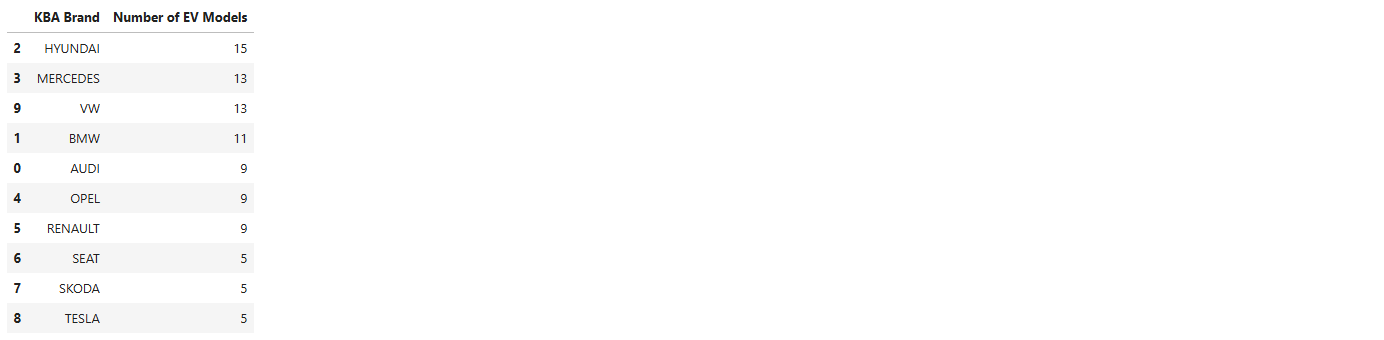
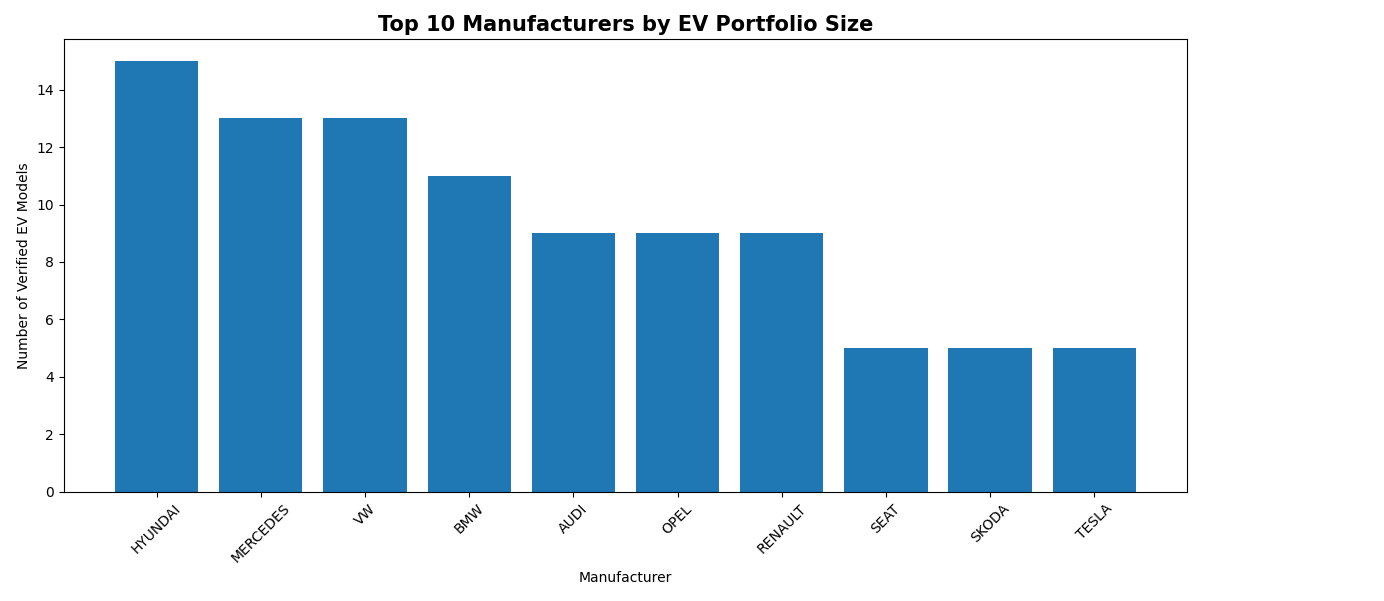
Hyundai, Mercedes-Benz, Volkswagen and BMW had some of the broadest portfolios.
A broad portfolio helps address more customer needs, but leadership also depends on pricing, technology and demand.
The principal charts explain growth, competitive position, model performance, segment demand and product strategy.
Shows how BEV registrations changed from 2020 to 2026.
Identifies the ten manufacturers with the highest cumulative registrations.
Ranks the most successful verified EV models.
Compares manufacturer contributions to cumulative registrations.
Reveals the importance of SUVs and other vehicle categories.
Compares annual manufacturer performance and growth.
Examines how the supply of verified EV models expanded.
Compares the breadth of manufacturer EV portfolios.
The analysis revealed clear patterns in market growth, competition, model success and consumer preferences.
Registrations increased strongly from 2020, despite a 2024 decline and incomplete 2026 data.
It recorded the highest overall registrations and the largest market share.
The Model Y and Model 3 were among the strongest-performing EV models.
The SUV category generated substantially more registrations than other segments.
Verified market introductions expanded strongly during key electrification years.
Success also depended on pricing, positioning and high-performing flagship models.
The findings support product, pricing, infrastructure and competitive intelligence strategies.
Continue investing in competitive electric SUVs while maintaining affordable compact options.
Evaluate whether each model contributes meaningful volume rather than focusing only on portfolio size.
Track annual registrations, market share and launches to identify threats and opportunities.
Combine attractive pricing with practical range, charging speed and infrastructure access.
Refresh the analysis regularly to support strategy, forecasting and policy decisions.
This project analysed Germany's BEV market using official KBA registration data enriched with a verified EV model database. The original dataset contained 3,374 records across 17 variables. After removing 40 exact duplicates, the cleaned analytical dataset contained 3,334 unique records.
Volkswagen held the highest cumulative market position. Tesla, BMW, Mercedes-Benz, Audi, Škoda and Hyundai also demonstrated significant presence. The Volkswagen ID.3, Tesla Model Y, Tesla Model 3 and Volkswagen ID.4/ID.5 family were among the strongest-performing models.
SUVs accounted for the largest registration volume. Model availability and manufacturer EV portfolios continued to expand, although portfolio size alone did not guarantee market leadership.
It should not be compared directly with complete calendar years.
Medium- and low-confidence mappings may contain ambiguity or aggregate categories.
PHEVs, hybrids and internal-combustion vehicles are outside the main scope.
Incentives, prices, charging access and economic conditions may influence trends.
Replace the Kaggle placeholder with your final published notebook URL.